Soosan Industries Stock Sold More and Kept Far Less of It
I opened Soosan Industries stock expecting a shrinking business priced accordingly. It trades at 0.54x book and 6.18x trailing earnings on the KOSPI, Korea’s main board, and companies at that valuation usually have an income statement that is contracting from the top down. This one is not. Sales for the six months to June 2026 came to KRW 178.29 billion, the highest first half in the four years of data I hold. What contracted was everything between that line and the bottom of the statement, and then the bottom itself went the other way.
One analyst estimate, measured two ways, gives two different answers about how this year is going.
| 39.76% | First-half operating profit of KRW 19.48bn against the 2026 estimate of KRW 49.0bn |
| 75.53% | First-half owner net income of KRW 41.39bn against the same report’s estimate of KRW 54.8bn |
| 35.77pp | The distance between them, which I calculated. Both come from one DS Investment and Securities report dated May 27, 2026 |
| Stance | Watching, no position. At a KRW 302.1bn market value this sits outside Korea’s top 100 by size and I do not take trading positions there |
Contents
Soosan Industries stock trades on an earnings figure I had to reverse engineer
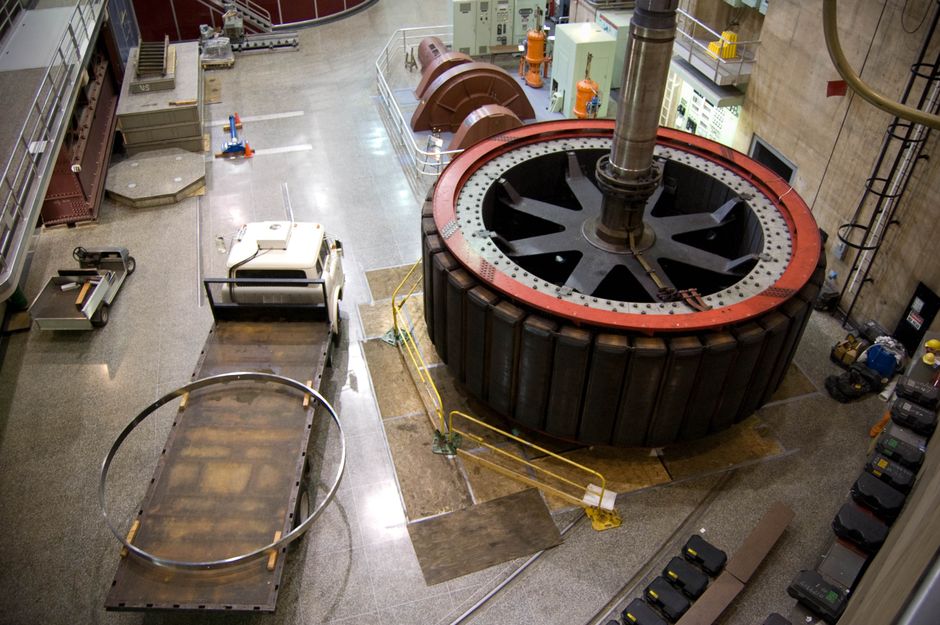
The company sells maintenance services to power plants. Planned overhauls, routine servicing and performance upgrades on thermal and nuclear generating equipment, sold mostly to Korea’s state generation companies and to Korea Hydro and Nuclear Power. It is listed on the KOSPI, which is the senior of Korea’s two boards; the KOSDAQ is the junior one, and this company is not on it.
The close on September 3, 2026 was KRW 21,150 against 14,283,688 shares outstanding, which multiplies to KRW 302.10 billion. At KRW 1,359.3 per US dollar, the Seoul weekly-session close on 2026-09-03 as reported by two Korean financial outlets, that is about USD 222.25 million. This is the only currency conversion in this piece; every other figure below stays in won.
The screen shows a price to earnings ratio of 6.18x. Dividing the market value by 6.18 gives KRW 48.84bn, and the closest match in the company’s filings is FY2025 net income attributable to owners of KRW 48.90bn, a difference of 0.042%. Consolidated net income for the same year was KRW 48.83bn, which does not close as cleanly. So the multiple is built on the owner figure. The distinction does not change anything here because the two are 0.15% apart, but I would not want to carry an unlabeled multiple into a company where minority interests are large.
Two progress ratios that do not agree
DS Investment and Securities published a note on this company on May 27, 2026, written by analyst Cho Dae-hyung. Buy rating, a KRW 41,000 valuation, and full-year 2026 forecasts of KRW 352bn in sales, KRW 49bn in operating profit and KRW 54.8bn in net income. The valuation is derived from KRW 3,840 of earnings per share at a 10.8x target multiple, described as a 30% discount to comparable companies.
The arithmetic in that report closes. KRW 3,840 times 14,283,688 shares is KRW 54.85bn, matching the net income line. KRW 3,840 at 10.8x is KRW 41,472, which is 1.15% above the KRW 41,000 figure carried on the front page, so the number appears to have been rounded down, though the report does not say so.
Half the year is now filed. Operating profit for the six months to June was KRW 19.48bn, which is 39.76% of the KRW 49bn estimate. Owner net income was KRW 41.39bn, which is 75.53% of the KRW 54.8bn estimate. One line is not yet at 40% of the year; the other is past three quarters of it. Both ratios use the same six months and the same report.
For the operating estimate to hold, the second half needs KRW 29.52bn. That is 1.5150x the first half of KRW 19.48bn, and 32.51% above the KRW 22.28bn this company actually produced in the second half of 2025. It is not an impossible number for a business whose overhaul work clusters unevenly through the year, but it is a demanding one, and nothing I found dates it to a specific quarter.
What argues against me
Six things push back on the reading above, and I think three of them are serious.
- The order book grew. On July 29, 2026 the company disclosed a contract amendment on planned maintenance work for the Shin-Kori 1 and 2 reactors, raising the value from KRW 35.53bn to KRW 70.06bn and extending the end date by a year to July 31, 2027. The counterparty is Korea Hydro and Nuclear Power. The filing states the revised amount equals 21.58% of 2023 consolidated sales, up from 10.94%.
- Sales are not the problem. Discrete second-quarter sales of KRW 92.62bn were the second largest of the fourteen quarters I reconstructed. Volume held; the conversion of that volume did not.
- The one analyst covering it expects operating profit to rise this year. KRW 49bn against KRW 43.08bn actually earned in 2025. My reading requires that estimate to be wrong.
- A collapsed quarterly margin has happened here before and reversed. The July to September 2024 quarter printed a 3.40% operating margin and the next one printed 15.05%. Judging a trend on one quarter would have been wrong that time.
- The balance sheet is not stretched. Liabilities to equity stood at 23.01% at June 30, 2026, and half-year interest expense was KRW 0.96bn against KRW 134.33bn of total liabilities.
- The dividend has risen three years running. Filed dividend history shows KRW 600 for fiscal 2022, KRW 800 for 2023 and 2024, and KRW 900 for 2025. Looking further back weakens this: fiscal 2020 and 2021 each paid KRW 1,000, so the payout has not yet returned to where it was.
The third item is the one that would cost me most. If the KRW 49bn estimate lands, the first-half margin compression was timing and my note here ages badly.
Soosan Industries stock next to a peer selling the same service
Listed pure plays in power plant maintenance are thin on the ground anywhere, so I looked for a company selling inspection and asset integrity work to industrial and energy customers. Mistras Group, listed on the NYSE under MG, is the closest I could find that reports comparable figures publicly.
| Measure | Soosan Industries | Mistras Group |
|---|---|---|
| Market value | KRW 302.10bn | USD 617.57m |
| Market value to sales | 0.8947 | 0.8355 |
| Net margin | 14.46% | 3.65% |
| Price to earnings | 6.18 | 23.57 |
Soosan figures use fiscal 2025 filed results and the September 3, 2026 close. Mistras figures are trailing twelve months as displayed on September 2, 2026, one US trading session earlier. Both ratio columns are my own division. No currency conversion was applied to either column; what crosses between them is the ratio itself.
The two sales multiples are 7.09% apart. The two net margins are 3.962x apart. That is the whole comparison in one line: the market is paying nearly the same price for a unit of revenue at both companies, and one of them turns almost four times as much of that revenue into net income. If a company converts revenue to profit four times better than a comparable peer and is priced at a quarter of the peer’s earnings multiple, the interesting question is not whether it is cheap. It is whether the conversion is durable.
Two limitations on that table. Mistras’ displayed earnings per share of USD 0.82 does not exactly match its trailing net income divided by its current share count, which gives USD 0.847, a 3.3% difference that I read as share count timing. And I did not verify the segment mix at either company, so “the same service” is my description of two business summaries, not a matched revenue breakdown.
Four first halves, and one of them behaves differently
Net income exceeding operating profit is where the two progress ratios diverge, so I put four first halves side by side.
| Six months to June | Operating profit | Net income | Net to operating |
|---|---|---|---|
| 2023 | KRW 27.34bn | KRW 26.98bn | 0.99x |
| 2024 | KRW 29.48bn | KRW 26.87bn | 0.91x |
| 2025 | KRW 20.80bn | KRW 14.77bn | 0.71x |
| 2026 | KRW 19.48bn | KRW 41.37bn | 2.12x |
Cumulative half-year figures from Korean regulatory filings, consolidated basis. The final column is my own division.
The 2026 gap is KRW 21.89bn. Net income is stated after tax, so the pre-tax amount arriving from outside operations is larger than that; I could not open the tax line, so I will not say how much larger.
I named two candidates and they covered a sixth of it
The company holds stakes in two other listed Korean companies. A Korean filings aggregator puts those at 33.19% of Soosan Sebotics and 19.10% of Soosan I and T as of March 17, 2026. If those are carried at equity, a share of each company’s profit flows into this one’s income statement.
Their filed first-half net income figures are KRW 8.24bn and KRW 5.10bn. Applying the stakes gives KRW 2.74bn and KRW 0.97bn, a combined KRW 3.71bn. That is 16.95% of the KRW 21.89bn I was trying to account for. The remaining KRW 18.18bn I did not locate.
I did establish that neither company is consolidated. Soosan Sebotics reported KRW 210.32bn of equity at June 30, 2026; consolidating it would put roughly KRW 140.5bn of minority interest onto this company’s balance sheet. The actual figure is KRW 2.53bn. The orders of magnitude settle that question.
So this section ends unresolved, and I would rather record that than round it off. A blank is more useful to me at the November filing than a plausible guess is at the September 3, 2026 close.
The spending side moved first
One line moved well before the margin did. Capital expenditure ran at KRW 3.42bn in fiscal 2022 and KRW 3.84bn in 2023, then KRW 11.01bn in 2024 and KRW 20.17bn in 2025. The 2025 figure is 5.894x the 2022 figure. Over those same four fiscal years annual sales moved from KRW 303.54bn to KRW 337.66bn, a multiple of 1.1124x. Capital spending multiplied 5.30 times as fast as the revenue it was meant to support, which is the ratio of those two multiples and not a growth-rate comparison.
That spending crossed operating cash flow in 2025. Cash from operations was KRW 11.23bn against KRW 20.17bn of capital expenditure, leaving free cash flow at negative KRW 8.94bn. The three preceding years were positive at KRW 14.80bn, KRW 37.25bn and KRW 56.37bn. It is the only negative year in the four I hold.
The first half of 2026 reversed that at the cash line: KRW 37.61bn of operating cash flow against KRW 12.51bn of capital expenditure gives KRW 25.11bn of free cash flow, or 8.31% of the KRW 302.10bn market value. So the cash statement and the income statement are pointing in opposite directions in the same six months, which is the second place in this company where two measures of the same period disagree. I do not know whether the 2024 and 2025 spending is what compressed the second-quarter margin through depreciation, because the account set I have does not carry depreciation separately. That is a question for the Q3 filing and not a conclusion here.
Soosan Industries stock has one analyst, which is itself a finding
The DS note is the only recent named estimate I could locate. I also found a March 2024 mention by KB Securities analyst Kim Hyun-kyum, but two-year-old numbers are not a forecast and I did not carry them forward. My own rule asks for two named houses before I lean on forward figures, and this piece does not meet it.
That matters more than a missing data point. When one desk carries a company, its estimate becomes the consensus by default, and there is no second view to disagree with it. I have written before about how much a peer median moves when one row leaves the table; a single-analyst consensus is that problem taken to its limit. I used the KRW 49bn estimate as something to measure against, and not as something to build a target on.
Screen fields for forward earnings, forward multiple and peer multiple are all empty for this company, which is consistent with thin coverage and not with a data outage.
What owning Soosan Industries stock from the US would involve
There is no American depositary receipt for this company that I could find. Access from the United States means buying the Seoul listing directly through a broker that offers Korean market access, which several US brokers do.
The practical constraint is depth, not eligibility. Foreign ownership stands at 2.72% and margin balance at 1.31%, both low, and a KRW 302.1bn company is small enough that ordinary position sizes move the quote.
The price itself sits 41.90% below its 250-session high of KRW 36,400 and 8.85% above the KRW 19,430 low. Measured from the same KRW 21,150 close, the twelve-month change is 3.2% lower and the six-month change is 19.43% lower, so most of the decline is recent and not a long slide.
Numbers I decided not to use in valuing Soosan Industries stock
Screen values that I could not rebuild from filed statements do not go into my reasoning. Four were set aside here.
- Enterprise value multiple of 2.51. Not a possible order of magnitude for a company with 23.01% liabilities to equity and a KRW 302.1bn market value.
- Book value per share of KRW 38,871. Multiplied by shares outstanding it gives KRW 555.22bn, which is 0.90% away from fiscal 2025 owner equity and 0.44% away from total equity. Neither closes. I quoted the 0.54x book multiple as a screen figure and did not rebuild it from an equity line.
- Raw payout ratio of 27.4%. KRW 900 per share divided by any earnings per share I hold gives 26.30%, which the screen also shows. I used that one.
- Free float of 14,286,000 shares. This exceeds shares outstanding of 14,283,688 by 2,312 shares. The direction is backwards, so market value was computed on shares outstanding.
The interest coverage field carries an unknown basis label, but 19.48 divided by 0.96 reproduces the displayed 20.27x, so I cite it only as a reproduction check. Earnings before interest, tax, depreciation and amortization is empty, which is normal because Korean filings do not carry depreciation in the account set the data comes from.
My stance on Soosan Industries stock and four conditions that end it
Watching, no position. Outside Korea’s top 100 by market value I do not take trading positions, so this is an observation note.
The judgment I hold is this. The discount here does not look to me like disappearing profit. It looks like profit that changed its source between 2024 and 2026, and I have accounted for under a fifth of that change. I do not buy what I cannot account for.
Any one of the following ends that judgment.
- Discrete third-quarter operating profit above KRW 10bn. The KRW 5.86bn printed in the second quarter would then be a single quarter and not a slope.
- Discrete third-quarter operating margin above 12.76%, which is the full-year 2025 figure.
- The Q3 filing showing that most of the KRW 21.89bn half-year gap between operating profit and net income comes from repeatable items. I am currently assuming the opposite.
- A second named brokerage publishing a 2026 operating profit estimate at or above KRW 49bn, which would remove the coverage-gap caveat I attached to everything forward-looking here.
The check date is November 16, 2026. The statutory deadline for the third-quarter report is November 15, which falls on a Sunday, so the next business day is when I will look. Korean exchanges also carry preliminary results two to three weeks ahead of the statutory filing for some companies, and I did not confirm whether this one publishes those.
What I will check when the next Soosan Industries stock filing lands
This piece produced a short table of half-year ratios: 0.99x, 0.91x, 0.71x, 2.12x. In November a fifth entry joins it, and where it lands decides which of the sentences above survives.
If third-quarter operating profit clears KRW 10bn and the margin returns toward 13%, the fifth entry looks like the first three and I delete the judgment paragraph; the second quarter becomes an incident. If operating profit stays near KRW 6bn while net income again runs well ahead of it, the fifth entry looks like the fourth and the question stops being about one quarter and starts being about what this company’s income statement now is. The third possibility is the one I have not priced: operating profit recovers and the net-to-operating ratio also returns below 1.0x, which would mean the first-half gap was a single event that has already passed through. That would make the KRW 18.18bn I failed to trace less interesting, and it would also mean my four conditions were pointed at the wrong line.
Writing the branches down before the date is the part that helps. On the day a filing arrives the price is on screen first and the table second, and I have found that deciding in advance which two series to compare is what keeps the reading honest. The same applies to choosing the measure before looking at the ranking it produces.
Sources
- Financial statements: Korean regulatory filings via the Financial Supervisory Service disclosure system. Half-year report receipt number 20260814001283; fiscal 2025 annual report receipt number 20260323001320. Data as of August 20, 2026.
- Price and screen metrics: Kiwoom data, September 3, 2026 close.
- Shin-Kori contract amendment: Korean business news report dated July 29, 2026, translated by me from the Korean.
- DS Investment and Securities note of May 27, 2026: original PDF and Korean press coverage of the same day.
- Affiliate stakes and filing list: GoInsider, a Korean disclosure aggregator, shareholding as of March 17, 2026.
- Mistras Group figures: stockanalysis.com company page, displayed September 2, 2026.
- KB Securities mention of March 20, 2024: Korean press report, not used as a forward estimate.